Investing, News
Nebius Stock Is Down 48% From Its October High Ahead of Its Nov. 12 Earnings
KEY POINTS
- Nebius reports third-quarter results before the market opens on Nov. 12, with the stock at $129.49, 48% below its Oct. 6 close of $249.87.
- If the third quarter lands at the $905.7 million consensus, Nebius needs about $1.1 billion of fourth-quarter revenue just to reach the low end of its $3.0 billion to $3.4 billion 2026 guidance.
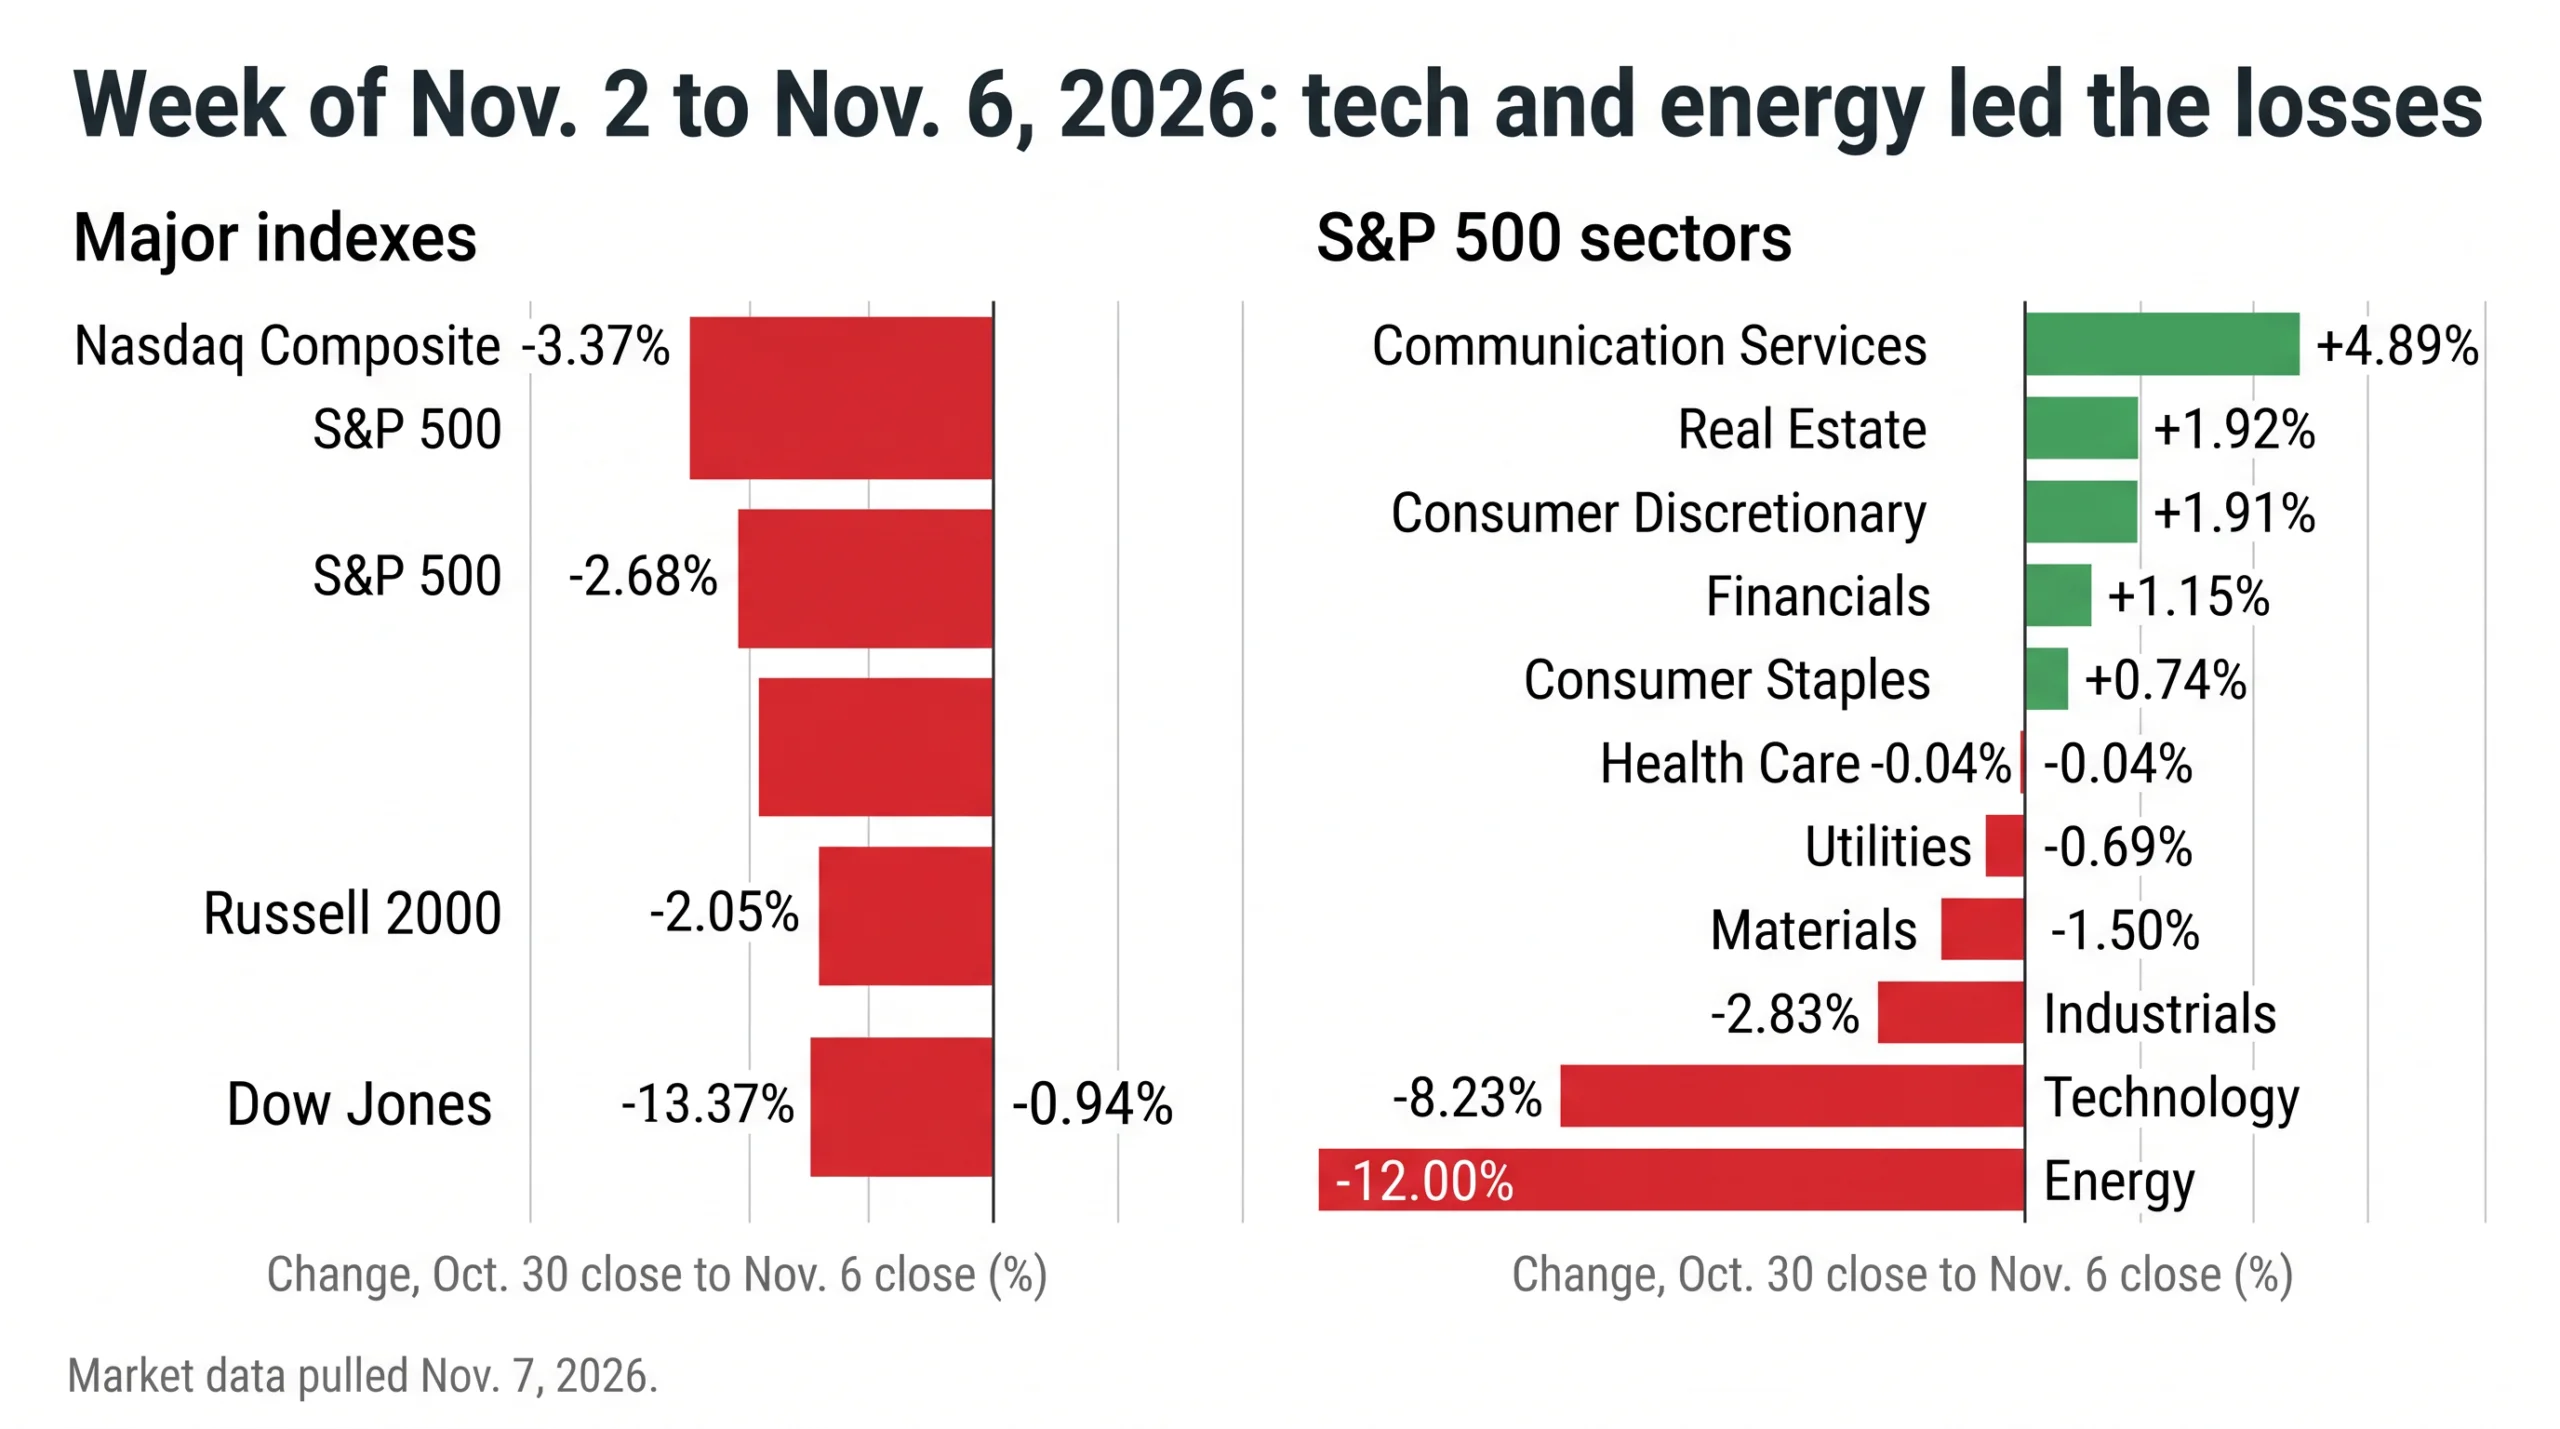
- A Nov. 5 report on Microsoft tightening oversight of neocloud projects sent the stock down 14.9% in one day, even though it described no change to Nebius’ own contract.
Nebius Group N.V. (NBIS) is set to report third-quarter results before the market opens on Nov. 12, and the stock is walking in 48% below its Oct. 6 close. Shares ended last week at $129.49, after a 14.9% drop on Nov. 5 and a 7.6% bounce on Friday.
The company confirmed the date, with the call set for 8:00 a.m. Eastern. That is a long way down for a stock that jumped 34% on its second-quarter report on Aug. 12, and almost none of the slide came from Nebius itself. So today I want to look at what actually happened, what the fourth quarter has to deliver, and where the funding math gets tight.
One Report Cost Nebius 15%, Yet No Contract Changed
The Nov. 5 drop started with a Bloomberg story. According to this recap of the report, Microsoft (MSFT) has tightened its oversight of neocloud data center projects, and Nebius was named among the providers under closer watch. The report did not describe any change to Nebius’ contract or any action against it.
The concrete moves involved other companies. Microsoft declined an option that would have more than doubled its Nscale compute deal in Texas, and it walked away from anchoring an Nscale site in Essex, England. Even so, Nebius closed at $120.37, down from $141.52 the day before, and CoreWeave (CRWV) fell 9.8% on the same day.
But why does one report with no new numbers matter this much? Because of how much rests on a single customer. The Microsoft agreement is worth $17.4 billion over five years, which is about 33 times the $529.8 million in revenue Nebius booked in all of 2025. In other words, a headline that changes nothing in that contract can still move the stock, because the market is pricing the risk that it someday does.
That risk is real, but it is not new, and it is not the same thing as a delivery problem. The better test comes from the numbers Nebius will put on the table on Nov. 12, starting with the fourth quarter.
The Fourth Quarter Has to Do the Heavy Lifting
Management reaffirmed its 2026 revenue guidance of $3.0 billion to $3.4 billion. First-half revenue was $981.3 million ($399.0 million in Q1 and $582.3 million in Q2), so the second half has to bring in between $2.02 billion and $2.42 billion. Analysts expect $905.7 million in Q3 and $1.46 billion in Q4, which adds up to about $3.35 billion for the year.
That Q3 estimate already means 56% growth over Q2, which is a big step on its own. The part I think gets overlooked is what it leaves for Q4. The table below shows the fourth-quarter revenue Nebius needs under three third-quarter outcomes, using the low, average and high analyst estimates.
| Q3 revenue outcome | Growth over Q2 | Q4 needed for $3.0B | Q4 needed for $3.4B |
|---|---|---|---|
| $876.6M (low estimate) | 50.5% | $1,142.1M | $1,542.1M |
| $905.7M (consensus) | 55.5% | $1,113.0M | $1,513.0M |
| $942.6M (high estimate) | 61.9% | $1,076.1M | $1,476.1M |
At the consensus Q3 number, the low end of guidance needs Q4 to grow about 23% from Q3. That sounds manageable. The top end needs about 67%, and the Street’s $1.46 billion Q4 estimate sits only $51 million below it. So the market is already penciling in something close to the best case for the fourth quarter.
To be fair, Nebius has said the big contracts are back-loaded. According to this earnings preview, management said the large second-quarter deals “come online late in the year and help 2027 more than 2026.” That is useful context for the guidance, and it is also why I would not read a Q3 that merely meets estimates as proof that the top end is safe.
There is a track record to weigh here as well. Nebius beat in Q2, with $582.3 million of revenue against a $573.9 million consensus and a loss of $0.12 per share against an expected $0.67 loss. But, as 24/7 Wall St. noted, revenue missed consensus in both Q3 and Q4 of 2025, so a clean beat is not something to take for granted.
I broke down the $7 billion to $9 billion annualized revenue target and how Nebius plans to pay for it in a recent video, so if you would rather watch than read, here it is.
Customer Concentration Is the Risk Behind the Sell-Off
Now, the concentration number is worth putting in plain terms. Three customers made up 24%, 21% and 14% of Q2 revenue, according to the same 24/7 Wall St. analysis. That is 59% of sales from three names.
Add the annualized revenue target and the stakes get clearer. Nebius exited June at $3 billion of annualized revenue and is aiming for $7 billion to $9 billion by December, which means adding $4 billion to $6 billion in two quarters. The cushion is the contract book: Nebius has said it has about $40 billion in customer commitments. The one concern that matters is timing, since a data center that slips a quarter pushes billed revenue out with it.
That is why a Microsoft headline hit the stock so hard. It touched the one assumption the whole year depends on, which is that signed capacity turns into billed capacity on schedule. Funding that build is the other half of the story.
Cash Sits Below Debt While Capex Plans Run to $25 Billion
Nebius ended June with $8.04 billion in cash. Against that sits roughly $10.06 billion of debt and lease obligations, including about $8.5 billion of long-term debt. Management plans $20 billion to $25 billion of capital spending this year and expects more than $9 billion of customer prepayments to help cover it.
The gap gets filled with debt, prepayments or new shares, and the share price decides how painful the last one is. Nebius raised about $2.8 billion in Q2 by selling stock at an average near $224, per the same analysis. At $129.49, raising a dollar takes about 73% more shares than it did at $224. So the lower the stock goes, the more every new dollar of equity costs the shares already outstanding.
Prepayments are the better tool, and Nebius leans on them, but customers renting short-term capacity are less likely to fund half a build upfront. I would rather see more multiyear, prepaid contracts on Nov. 12 than another loan.
What the Nov. 12 Report Needs to Show
Wall Street is still far above the share price. The consensus price target is $281, about 117% above $129.49 (per 24/7 Wall St.), and of the 21 analysts tracked, 14 rate the stock a Buy or Strong Buy, 5 a Hold and 2 a Sell or Strong Sell. I report those as news, not as a view of my own, and targets this far above the price tend to move only after the numbers do.
So there are four things I will be looking for. First, Q3 revenue against the $905.7 million consensus, and how much it leaves for Q4. Second, connected power against the 800 MW to 1 GW year-end target. Third, any word on delivery schedules for the Microsoft capacity. Fourth, how Nebius plans to fund the rest of its $20 billion to $25 billion budget.
If those four line up, the Nov. 5 drop will look like a reaction to a headline. If they do not, the market was right to price in more risk, and Nebius will have to show it at the next report.
This article is for informational and educational purposes only. It is not financial, investment, tax or legal advice, and it is not a recommendation to buy, sell or hold any security. I am not a registered investment advisor, so consult a licensed professional before investing. On the date of publication, I had positions in Microsoft/MSFT. Investing involves risk, including the possible loss of principal, and past performance does not guarantee future results. Analyst estimates, price targets and the valuation scenarios in this article are illustrations based on assumptions, not predictions, and actual results may differ materially. Market data pulled November 8, 2026. Figures may be delayed or contain errors and change quickly, so verify current numbers before acting. Analyst ratings and other third-party views are reported as news and are not endorsed by me. Information may have changed since publication.